April 2026 Newsletter – A Tale of Two Asset Classes
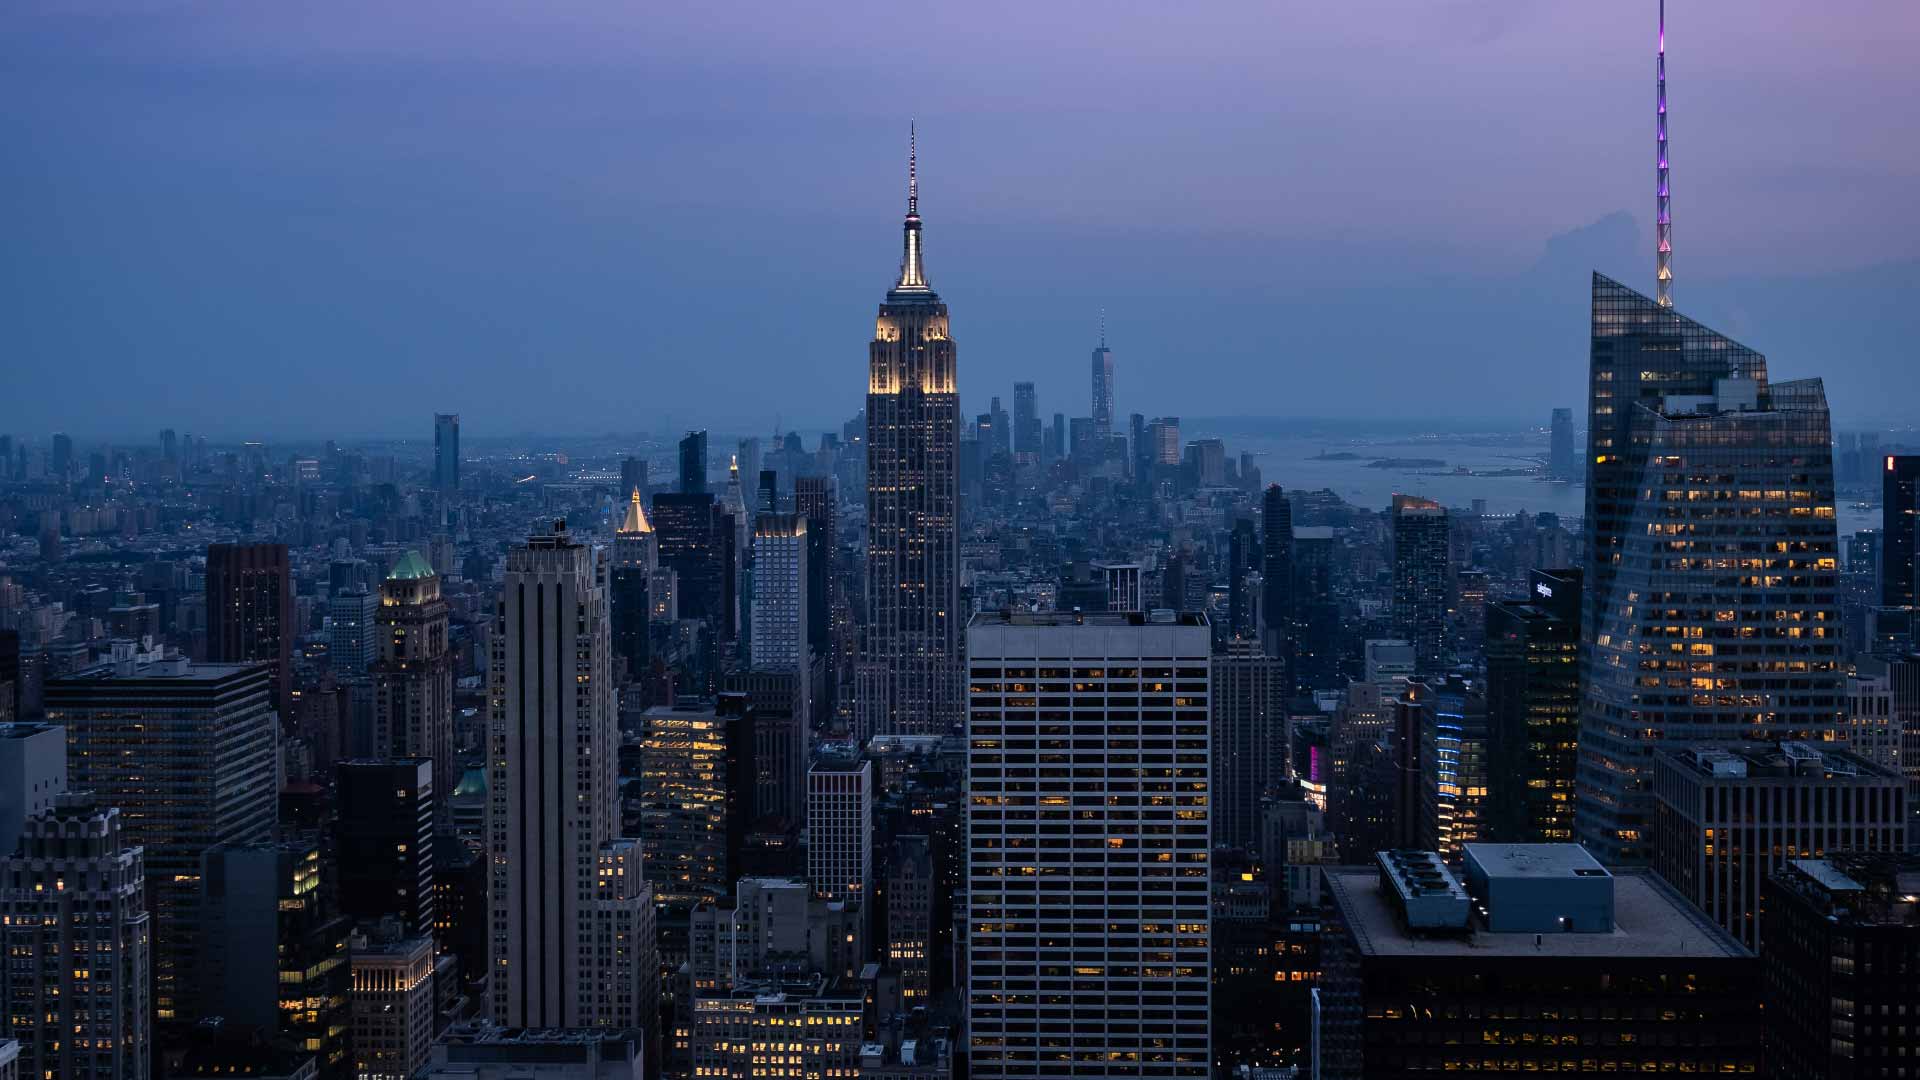
The Manhattan office market continued to strengthen throughout April and beginning into May 2026, with improving leasing velocity, tightening availability, and rising rents. The recovery is increasingly uneven: premier buildings in highly desirable markets such as Midtown, Hudson Yards, Park Avenue and the World Trade Center are thriving, while older commodity buildings continue to struggle with elevated vacancy and conversion risk.
Key Manhattan Metrics (Q1 / April 2026)
| Metric | Manhattan Overall |
| Overall Availability Rate | 13.4%–14.6% |
| Average Asking Rent | $73–$78 PSF |
| Quarterly Leasing Volume | 12.9M SF (Q1 2026) |
| April Leasing Activity | 3.6M SF |
| Net Absorption | Positive 2.0M SF (Q1) |
| Sublease Availability | Declining materially |
Key trends:
- Manhattan availability has fallen for eight consecutive quarters
- Available office inventory has declined more than 25M SF since early 2024
- Leasing demand is at its strongest level since 2019
- AI, legal, finance, and media tenants remain major demand drivers
The “flight to quality” trend continues to accelerate across the office market, with demand heavily concentrated in new construction, trophy towers, and highly amenitized Class A properties. Tenants are prioritizing buildings that offer modern HVAC systems, strong ESG credentials, outdoor space, and premium food and wellness amenities. As a result, availability within top-tier assets is tightening rapidly due to limited new development activity, tenants expanding within their existing footprints, and the continued reduction of large available blocks.
Leasing activity also remained strong in April, with Manhattan office leasing reaching approximately 3.6 million square feet — roughly 30% above the 10-year monthly average — signaling continued momentum in the market despite broader economic uncertainty.
At the same time, commodity office buildings continue to face significant challenges. Older Class B and Class C properties lacking modern infrastructure, ESG compliance, quality amenities, and efficient floorplates remain under pressure and are increasingly being considered for residential conversion, repositioning, demolition, or distress sales.
As availability continues to decline in premier buildings and key neighborhoods, tenants are facing increasing competition for high-quality office space, along with upward pressure on rents. While market conditions remain outside of a tenant’s control, navigating today’s environment requires a proactive and strategic approach. We can provide experienced tenant representation that can play a critical role in identifying opportunities, overcoming supply constraints, and securing favorable outcomes in an increasingly complex market. In any market, our message remains the same: Organizations that begin evaluating and executing their office strategies early are consistently best positioned
We invite you to watch the video linked below and contact us for a complimentary lease review or space planning consultation to explore how early planning can benefit your organization.